SavingMoney Stories
How I manage my moneyA reserve for being the only name on the bills
Teresa, a 58-year-old civil servant living in Northampton, is navigating the final decade of her career. With an annual income of £41,700 and a monthly mortgage of £640, she is focused on building an emergency reserve of £2,700 and managing irregular household costs, such as a £600 appliance replacement.
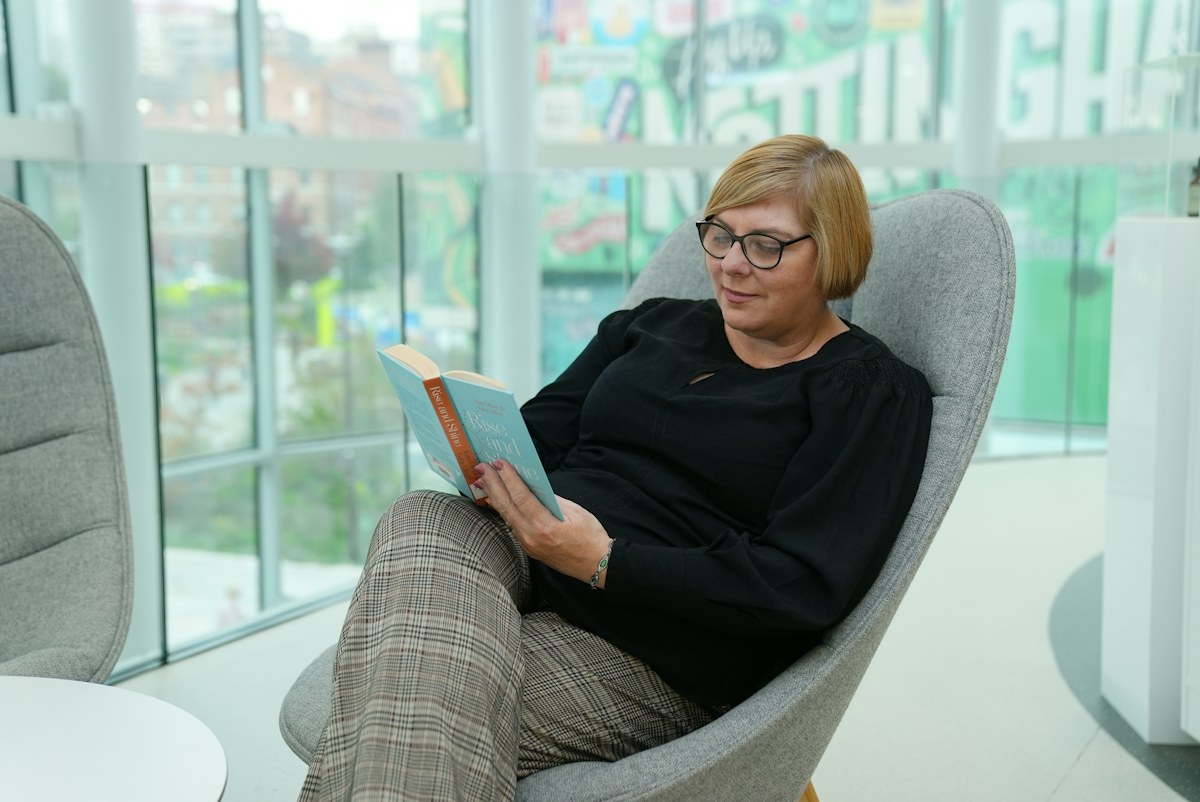
- NameTeresa
- Age58
- LocationNorthampton
- OccupationCivil Servant
- Annual Income£41,700
- AccommodationOwn home with mortgage
- Relationship statusSingle
A singular responsibility
Living alone in Northampton, the weight of the household rests entirely on my shoulders. At 58, I have a steady job as a civil servant with an annual income of £41,700, yet the peace of mind I seek is elusive. My mortgage of £640 a month is manageable, but the unexpected costs of maintaining a home always loom.
Preparing for the unexpected
My emergency fund stands at £2,700. It is a modest cushion, but it makes me feel secure. I recently had to address a £600 washing-machine replacement, which felt like a significant drain. It served as a harsh reminder that regardless of my household size, the costs of essential appliances are not adjusted to my level of income.
Structured savings for the future
I have committed to monthly savings of £95. It is not a fortune, but it is consistent. I treat this payment with the same gravity as my utilities or my mortgage. I am also trying to build a list of people I could call if I were ever unable to handle practical tasks in a disruption. It is a strange thing to plan for, but it is necessary.
I treat this monthly saving with the same gravity as my utilities or my mortgage.
Approaching later working life
There is a pervasive assumption that a late-career professional has everything sorted, but that is far from my reality. My job is demanding, and while I do not see my employment as fragile, I do see the importance of liquidity. I need to ensure that if my income were to shift, my obligations would not overwhelm me.
Managing the trade-offs
Every month, I review my list of obligations and my savings. There is always a trade-off between enjoying my current life and preparing for a time when I might want to slow down. Nothing is set in stone, and the balance is never perfect. I am simply trying to remain the master of my own finances while I am the only name on the bills.
The stories on How I Manage My Money are personal experiences and general information. They are not personalised financial advice.