RetirementMoney Stories
How I manage my moneyUsing money for ordinary pleasure instead of only preserving it
At 87, Frank balances the need for security with the desire to enjoy his years in his Scarborough home. With £7,200 in accessible savings and an annual income of £20,800, he is learning to make room for small pleasures without ignoring the costs still ahead.
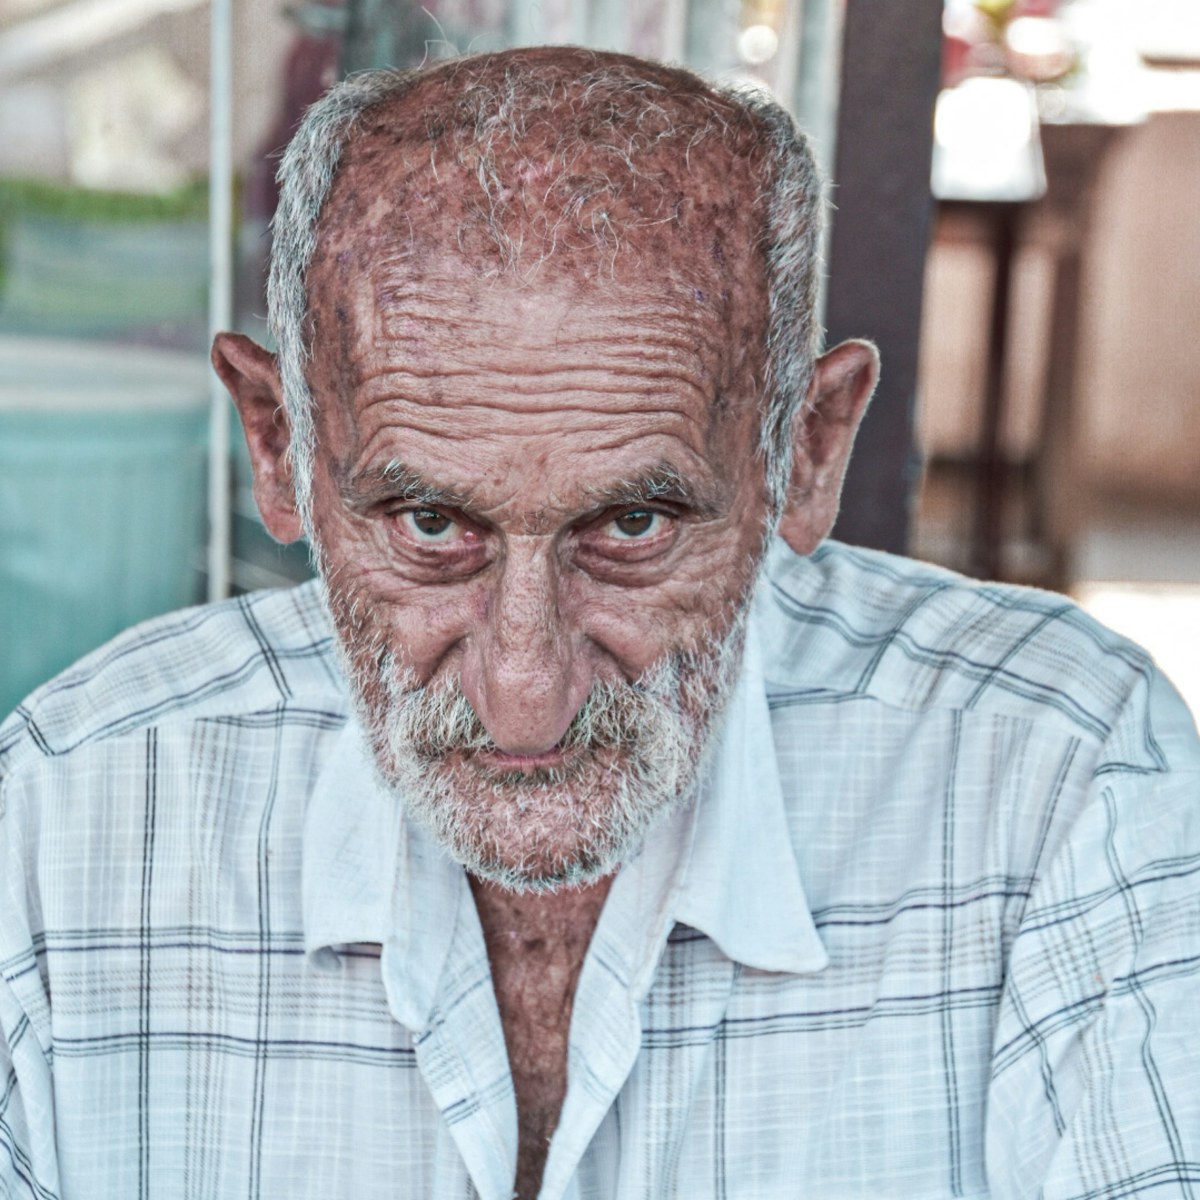
- NameFrank
- Age87
- LocationScarborough
- OccupationRetired
- Annual Income£20,800
- AccommodationOwn home no mortgage
- Relationship statusWidow
Finding meaning in small costs
I am 87 years old and I have lived in my Scarborough home for decades, completely mortgage-free. My annual income is £20,800, which is enough to keep me comfortable, but I often find myself caught in a stubborn habit of preservation rather than living. I currently hold £7,200 in accessible savings, and I am trying to learn how to loosen my grip on them to make my weeks feel more meaningful. It is a strange feeling, having been taught for so long to save for a rainy day, only to realise that the rainy days have mostly passed.
The cost of an occasional lunch
Recently, I finally treated myself to an £18 lunch at a local cafe. It was a simple, lovely experience, but immediately afterward, I worried if I was being reckless. Should I have been saving that money for a larger emergency or a structural repair that might pop up at any time? It is a constant, exhausting tug-of-war in my mind. I struggle to distinguish between necessary caution and an unnecessary deprivation that serves no real purpose in my current life.
Budgeting for joy
To combat this anxiety, I have started to allocate a specific £45 a month outing budget in my notebook. It feels much safer when it is explicitly labelled and separated from my general housekeeping funds. By knowing that the outings are pre-funded, I can enjoy a trip out or a visit to the theatre without the looming, cold fear of dipping into my reserves. It is a necessary administrative layer to make sure I am not just existing, but actively participating in the world around me.
I am teaching myself that spending money on small, meaningful moments is a valid use of my savings, even at my age.
Maintaining the home
Owning my home means I am solely responsible for dealing with every unexpected repair, and I must maintain a robust reserve for that eventuality. I am always trying to balance that dedicated repair fund with the small pleasures that actually make my weeks enjoyable. If the roof leaks, I need money, but if I want to have a nice afternoon, I also need money. It is a balance that feels perpetually precarious, even when my income remains steady.
The unresolved balance
There is no one telling me how much is actually enough at this stage. I do not have relatives weighing in on how I should spend my money, and I have no interest in worrying about what is left behind for others. The real challenge is finding the right level of comfort now, without knowing what the costs of the future might be. I am slowly teaching myself that spending money on small, meaningful moments is a valid use of my savings, even at my age.
The stories on How I Manage My Money are personal experiences and general information. They are not personalised financial advice.